
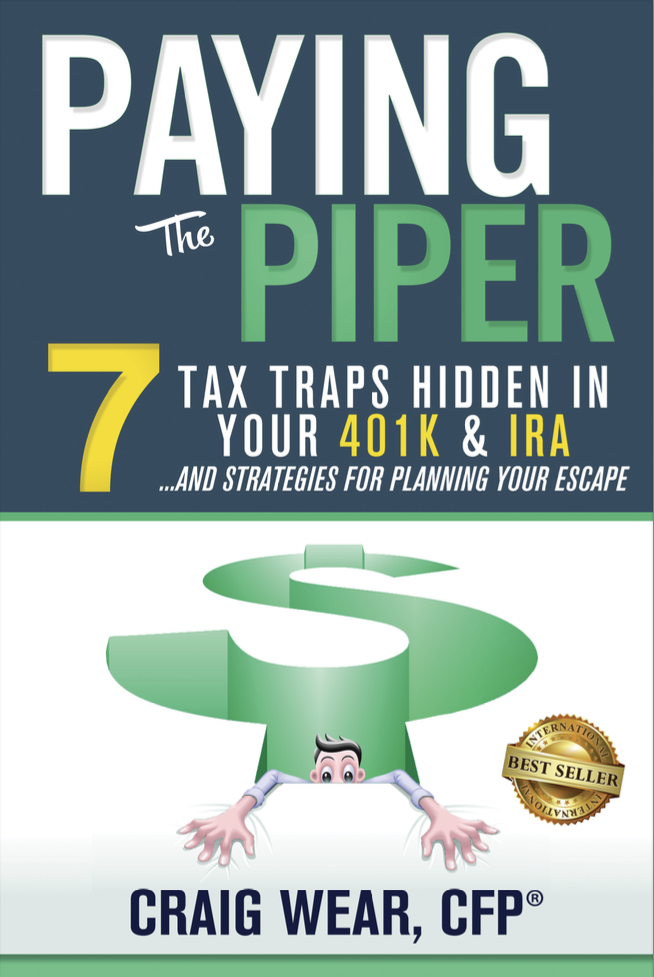
Every $1 million in your IRA has more than $800,000 of tax hidden inside it.
Craig Wear’s first book shows you where the tax is buried in your 401(k) and IRA, how large your share of it is, and the four ways out.
Arrives in about two minutes. No cost, no card, no subscription.
You did everything you were told. That’s the problem.
You maxed the 401(k). You took the match. You never touched it. Every article, every HR seminar, every advisor said the same thing, and you listened for forty years.
Nobody mentioned the second half of the arrangement.
A 401(k) deduction is not a gift. It is a deferral, and the terms of that deferral are set by whoever is writing tax law when you finally take the money out. You made a deal with the IRS and they left the interest rate blank.
Little did I realize at the time that I was setting a trap for myself.
$823,187 on a $1,000,000 IRA.
Tax on the distributions you’re required to take. Not the ones you want. The ones the IRS calculates for you, starting at 73.
Tax on the growth of money you didn’t need. You took the distribution, paid the tax, reinvested it, and now it’s taxable every year for the rest of your life.
Tax paid by your children. Under the ten-year rule, usually during their highest-earning decade.
Assumptions, in full: holder age 60 at retirement; $1,000,000 traditional IRA growing at 5% annually; 25% effective tax liability; required distributions reallocated to a taxable account at 5%; holder and spouse both living to age 90. Change any assumption and the number moves. Your figure will differ.
That is not a projection about the market. It’s arithmetic on money that is already in your account.
Seven traps, and four ways out.
The seven tax traps
- Little or no control over when you’re taxed
- Required distributions: the day the piper comes
- Distributions colliding with rising tax rates
- The bill your heirs inherit
- What it does to your Social Security
- What it does to your Medicare premiums
- The hidden cost of every large purchase
Four ways out, in order of impact
- Just Say No: stop compounding the problem, without giving up a dollar of the company match
- Stash the Cash: deliberately build the after-tax balances you’ll need later
- Free Fruit: the Roth option most people have and don’t use
- Set Yourself Free: conversions, and why Craig spent the next fifteen years on this one
Plus the three factors that decide which applies to you: your age, what you’ll actually spend from these accounts, and how much is in them.
A $10,000 purchase costs $13,125
Because you pay tax on the money you withdraw to pay the tax. Chapter 7 walks the cycle.
Tom and Betty needed $10,000
The IRS made them take $100,000 a year. One story, and the whole argument.
Seeds and oranges
You can pay for the seed once, or pay for every orange, every year, forever.
This book was published in 2019. Some of the tax code has moved since.
Required Minimum Distributions now begin at 73, not 72. Roth 401(k)s no longer require lifetime distributions. And the 2017 tax rates this book expected to expire at the end of 2025 were instead made permanent.
The diagnosis hasn’t changed. If anything, permanent rates made it more urgent: the deadline everyone was waiting on simply disappeared, and most people took that as permission to do nothing.
So we’ve included a short companion: What Changed Since 2019. Two pages, every number that moved, and what it means for your plan. It comes with the book.
Both files, free, in about two minutes.
Paying the Piper, the full book, full-color PDF. What Changed Since 2019, the two-page currency companion.
We don’t sell or share your address, and there’s nothing to cancel, because this isn’t a trial. You’ll also get Craig’s occasional notes on Roth conversion strategy, and you can stop those with one click at any time.
No cost. No card. Delivered in about two minutes.
Where most readers go next.
The current book
Roth Conversion Reset picks up where this one ends: what to do about it now that the rates are permanent, plus charitable giving, trusts and what your heirs actually inherit.
Run your own number
The RMD calculator shows what your account is scheduled to distribute, and what that does to your taxable income, starting at 73.
Find out what’s hiding in your account.
Free PDF, plus the 2026 currency companion. About two minutes.
Q3 Advisors, LLC is a Registered Investment Advisor. Paying the Piper was published in 2019; tax figures and thresholds within it reflect the law in effect at that time. See the accompanying What Changed Since 2019 companion for current rules. Information presented is for educational purposes only and does not constitute tax, legal or investment advice. Outcomes depend on individual circumstances. Projected figures are modeled estimates based on client analyses and are not a guarantee of future results. Consult your own tax professional before acting.